


Global geopolitical risk through a US news lens
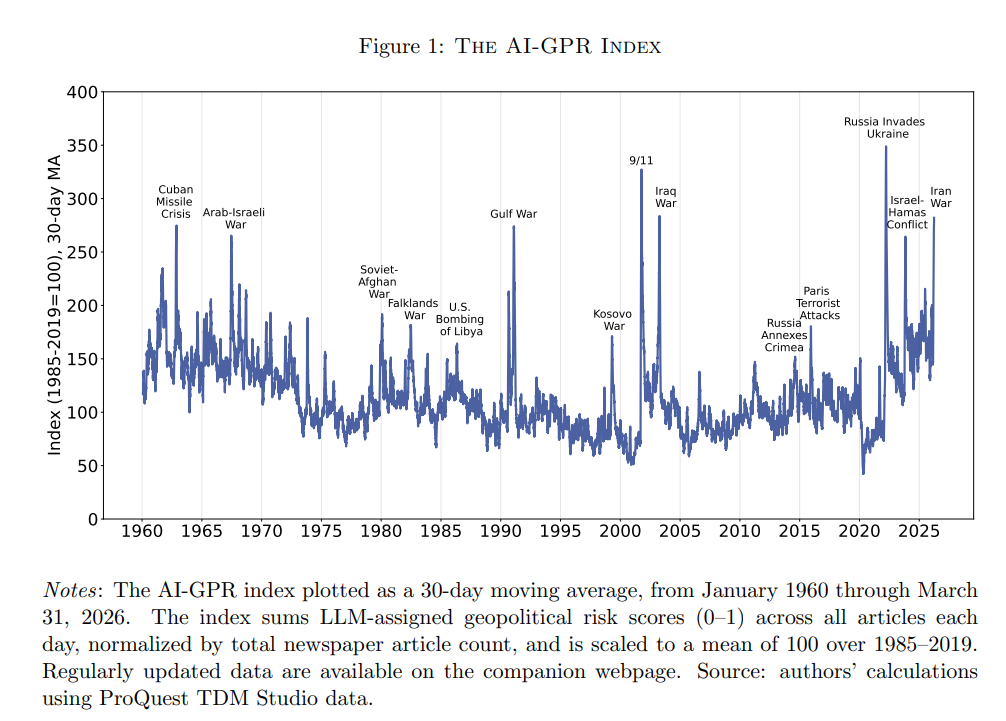
Matteo Iacoviello and Jonathan Tong examine whether AI’s understanding of news content produce a more accurate measure of geopolitical risk than traditional keyword-based methods.
Their methodology consists of:
- Data: Approximately 4.6 million articles from the New York Times, Washington Post and Chicago Tribune over 1960–2025, selected through a broad keyword screen.
- AI classification: GPT-4o mini evaluates each article’s headline and opening text, assigning a geopolitical-risk intensity score from 0 to 1 based on context, rather than keyword matches alone.
- Index construction: Scores are aggregated daily, divided by total newspaper output and normalised to average 100 over 1985–2019.
- Decomposition: Additional classifications distinguish threats from realised events, identify geopolitical oil-supply disruptions, and measure country-specific and directed bilateral risks.
- Validation and applications: The authors compare scores with human assessments and alternative AI models, then use regressions, a structural VAR and local projections to examine stock returns, oil shocks and bilateral trade.
Findings
- Improved measurement: The AI-based index captures relevant coverage missed by keyword searches and excludes more irrelevant references. Its scores correlate at 0.85 with human assessments, and the resulting index exhibits less day-to-day noise than the conventional measure.
- Financial markets: Higher geopolitical risk is associated with lower US stock returns. Persistent threats weigh on returns, whereas realised events matter primarily when they are unexpected.
- Oil and trade: Identified geopolitical oil shocks raise oil prices and consumer prices while reducing US output. A one-standard-deviation increase in bilateral geopolitical risk is followed by a gradual contraction in bilateral trade, reaching approximately 3.5% after two years before reco
The central contribution of this paper is contextual measurement: assessing what an article says about geopolitical risk, rather than simply whether it contains particular words. Nevertheless, the index reflects coverage in US newspapers, not a geographically neutral assessment of global risk.
The AI-GPR Index: Measuring Geopolitical Risk using Artificial Intelligence
Authors: Matteo Iacoviello, Jonathan Tong
From: Federal Reserve Board of Governors, University of Wisconsin
Geoeconomic tensions through a European news lens
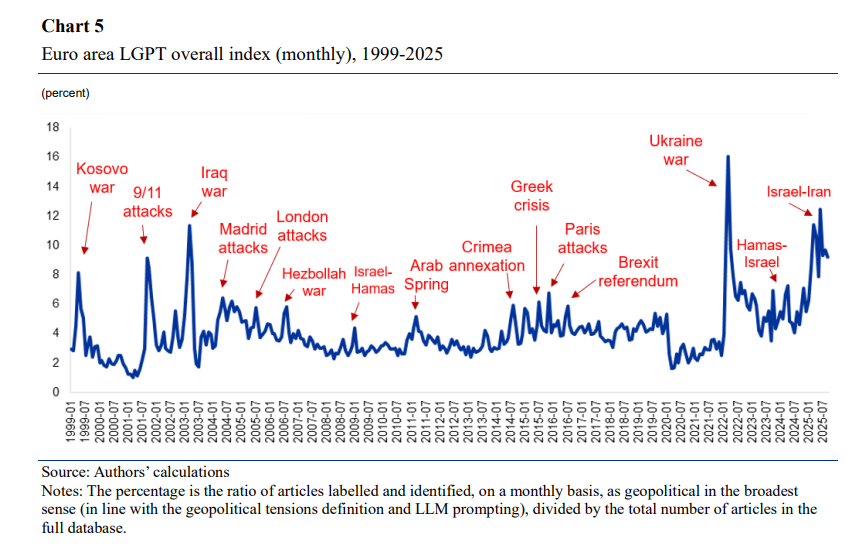
Demosthenes Ioannou, Raffaele Prioriello, and Agha Durran examine whether AI distinguishes geopolitical conflict from the use of economic tools for political purposes, and whether that distinction helps explain euro-area economic outcomes.
Their methodology consists of:
- European news sources: The authors assemble nearly 20 million newspaper articles, in their original languages, from France, Germany, Italy and Spain, focusing on 1999–2025.
- Two-stage AI classification: A fine-tuned multilingual EuroBERT model screens for relevant articles; GPT-4o then separates geopolitical tensions, such as armed conflict, from geoeconomic tensions involving economic leverage or coercion.
- Detailed indices: Geoeconomic articles are classified into trade, energy, finance or technology. The indices measure relevant articles as a share of total newspaper coverage, providing national measures and a euro-area aggregate.
- Economic application: A monthly Bayesian structural VAR estimates responses of euro-area output, consumer prices and financial variables, assuming tension shocks can affect other variables immediately, but receive feedback only with a lag.
Findings
- Geoeconomics adds distinct information: Its index captures episodes, including the euro-area debt crisis and trade disputes, that are less prominent in conventional geopolitical-risk measures.
- The source matters: Energy-related tension shocks reduce activity and raise consumer prices. Trade-related shocks also weaken activity but generate disinflationary pressures.
- Large shocks matter disproportionately: An additional nonlinear exercise suggests that larger geoeconomic shocks produce disproportionately stronger and more persistent economic effects. The authors present these economic applications as illustrative rather than exhaustive.
Comparison of the two papers
The useful contrast is intensity versus type of tension: Iacoviello and Tong score geopolitical-risk intensity using US newspapers, whereas Ioannou et al. classify tensions using European multilingual sources and explicitly separate geopolitical from geoeconomic developments.
Measuring geoeconomic tension: a large-language-model approach for the euro area
Authors: Demosthenes Ioannou, Raffaele Prioriello, Agha Durran
From: ECB
