



Interest-rate risk, bank capital, and the transmission of monetary policy
Jorge Abad, Saki Bigio, Salomón García-Villegas, Joël Marbet, and Galo Nuño analyze the way heterogeneity in banks’ exposure to interest-rate risk shapes the transmission of monetary policy to bank lending and financial stability.
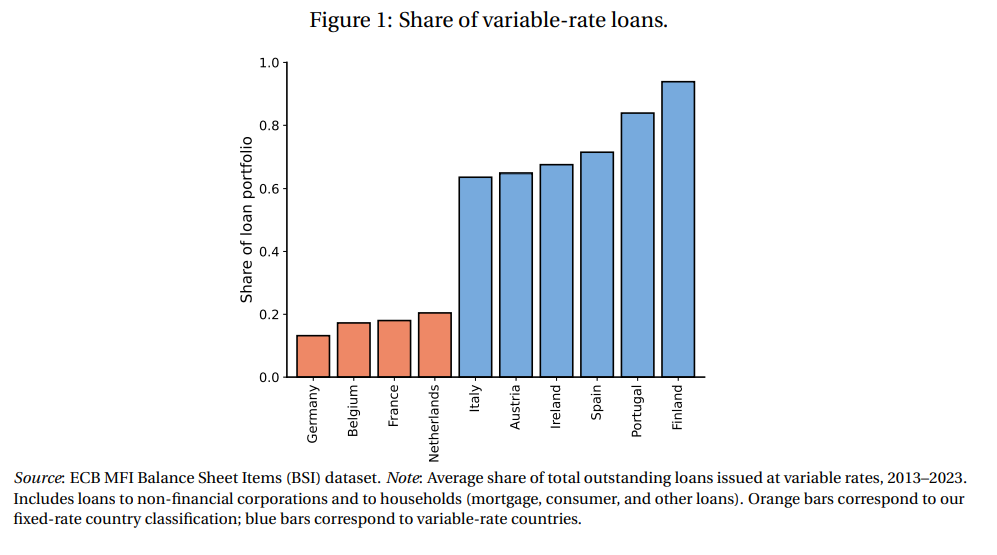
The authors develop a quantitative macroeconomic model featuring heterogeneous banks, long-term loans, short-term funding, idiosyncratic loan defaults, and regulatory capital and liquidity requirements. They compare two counterfactual banking systems: one dominated by fixed-rate loans and another by variable-rate loans.
The model is calibrated to euro-area balance sheets and the cross-sectional distribution of bank capital ratios. Its predictions are assessed against impulse responses estimated through local projections for ten large euro-area economies, divided according to whether fixed- or variable-rate lending predominates. The authors then conduct counterfactual exercises involving lower default-risk dispersion, the release of countercyclical capital buffers, and more gradual monetary tightening.
Findings
Interest-rate exposure affects monetary transmission only when banks are sufficiently close to their regulatory solvency thresholds. When rates rise, fixed-rate banks face higher funding costs while income from existing loans remains unchanged. Their net interest margins and capital consequently decline, pushing weak banks closer to regulatory limits and inducing sharper deleveraging. Variable-rate banks reprice existing loans more quickly, improving margins and strengthening capital buffers.
As a result:
- Lending contracts about one-third more strongly in the fixed-rate economy.
- Monetary tightening increases bank-failure risk under fixed-rate lending but reduces it under variable-rate lending.
- Banks closest to their capital requirements account for most of the difference.
- Releasing countercyclical capital buffers can moderate the credit contraction.
- A more gradual tightening path substantially reduces bank-failure risk in fixed-rate systems by giving banks time to adjust their balance sheets.
The Heterogeneous Bank Lending Channel of Monetary Policy
Authors: Jorge Abad, Saki Bigio, Salomón García-Villegas, Joël Marbet, Galo Nuño
From: ECB, UCLA, Cunef University, Banco De España
How unrecognized bank losses amplify monetary tightening
Antonio De Vito, Benedikt Kagerer, Cosimo Pancaro, and Alessio Reghezza analyze the way unrealized securities losses contribute to heterogeneous bank-lending responses to monetary tightening.
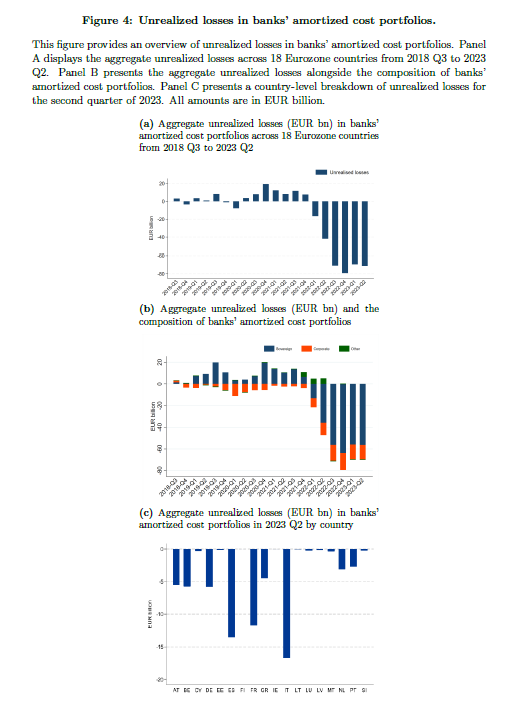
The authors combine confidential ECB supervisory data with AnaCredit loan-level information, producing more than five million bank–firm–quarter observations covering 82 banks and 411,965 firms across 18 euro-area countries from 2021 Q3 to 2023 Q2. Unrealized losses are calculated security by security as the difference between nominal and market values and then aggregated at the banking-group level.
Using the ECB’s rapid 2022–2023 tightening cycle, they apply a difference-in-differences strategy comparing how banks with different unrealized losses changed their lending to the same firm.
Findings
- Banks with larger unrealized losses reduced lending more sharply after monetary tightening began. A one-percentage-point increase in unrealized losses relative to assets was associated with approximately a one-percentage-point additional decline in lending growth.
- The effect was substantially stronger among banks with: a) Low liquidity buffers; b) Limited capital headroom; c) Greater reliance on uninsured deposits
- Banks responded by strengthening their capital positions and passing more of the policy-rate increase to depositors. Interest-rate hedging could offset the adverse effect on lending, while smaller firms, having fewer alternative funding sources, experienced the largest credit contraction.
- The authors show that accounting rules do not fully insulate banks from interest-rate risk. Even when valuation losses remain unrecognized in reported capital, they weaken banks’ capacity or willingness to lend, especially when banks have limited capital or liquidity, unstable funding, and insufficient hedging.
Hidden Weaknesses: The Role of Unrealized Losses in Monetary Policy Transmission
Authors: Antonio De Vito, Benedikt Kagerer, Cosimo Pancaro, Alessio Reghezza
From: University of Bologna, University of Cambridge, ECB
