


Are banks’ environmental disclosures consistent with their lending activities?
European regulators and institutional investors have pressured banks to reduce the financing of brown industries and align their lending activities with the goals of the Paris Climate Agreement. Banks, through their environmental disclosures, are touting about their climate governance, strategy, and impact. But do these disclosures give a complete picture of the banks’ lending decisions? This is the question Giannetti et al.are answering in this paper. They use data from the credit registry recently launched by the European System of Central Banks, Anacredit, which covers granular information on new loan issuance and credit exposures by Euro area banks as well as detailed data on borrowers’ characteristics. The environmental disclosures of the systemic banks are taken from banks’ investor reports.
We find that banks that portray their activities as more sustainable extend more credit to borrowers in brown industries and borrowers with higher emissions in general. This pattern is most pronounced for smaller borrowers, indicating that going beyond the largest borrowers and focusing on the whole bank loan portfolios is crucial to evaluate the emissions of banks’ portfolios. We further show that the disconnect between banks’ environmental disclosures and brown lending is not offset by a greater lending activity in green industries, further supporting that disclosures exaggerate banks’ environmental stewardship.
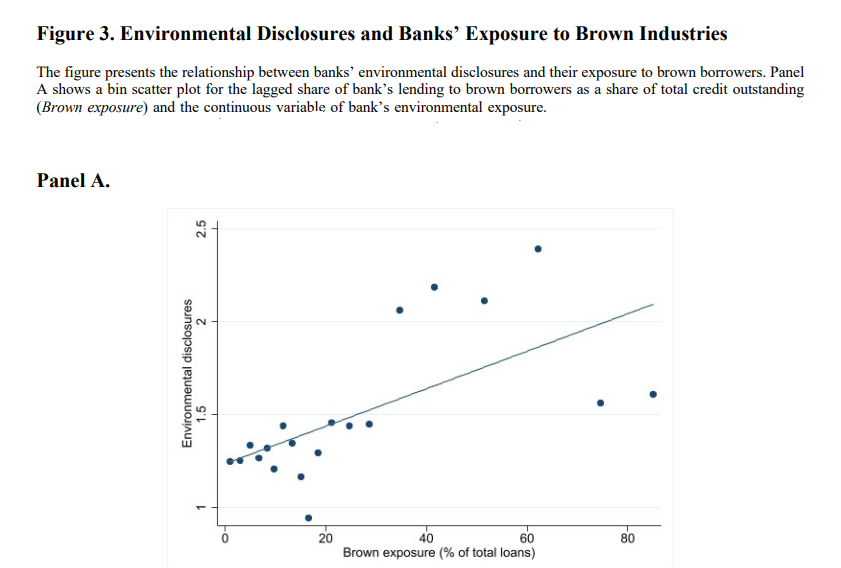
‘Glossy Green’ Banks: The Disconnect Between Environmental Disclosures and Lending Activities
Authors: Mariassunta Giannetti, Martina Jasova, Maria Loumioti, Caterina Mendicino
From: Stockholm School of Economics, Columbia University, The University of Texas at Dallas, European Central Bank
Who invests in green projects or assets?
In this paper, Fricke et al. construct a unique dataset that enables them to explore the relationship between the pricing of green bonds and their ownership structure. Their sample includes 161 green conventional bond pairs from issuers domiciled in developed economies over the period from January 2015 up until March 2022. They then combine this sample with confidential data on the dynamic ownership structure of each bond by investor group from the Eurosystem’s Securities Holdings Statistics. The authors find that the average yield differential between a green bond and its conventional twin on the secondary market, the “greenium,” amounts to roughly minus 3 basis points across our sample.
We draw the tentative conclusion that banks (or their clients) pay a significant greenium because they hold specific green bonds for motives other than green preferences. Examples may be market making, underwriting or liquidity management activities. The trade-off between offering such financial intermediation services and avoiding the greenium may be particularly relevant, for instance, when operating in the segment of small or young bonds.
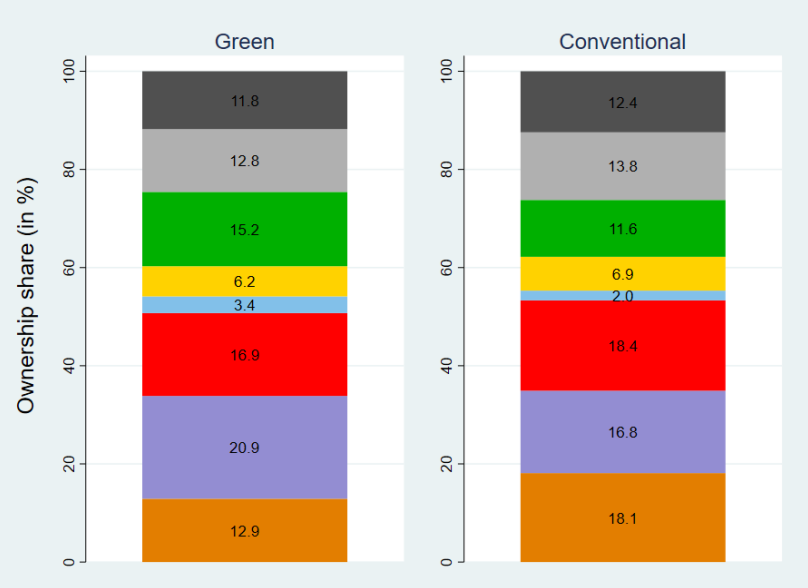

Who pays the greenium?
Authors: Daniel Fricke, Stephan Jank, Christoph Meinerding
From: Deutsche Bundesbank
